When completing any type of development project, you will need funds to
a) Purchase the land/property
b) Complete the build/refurbishment
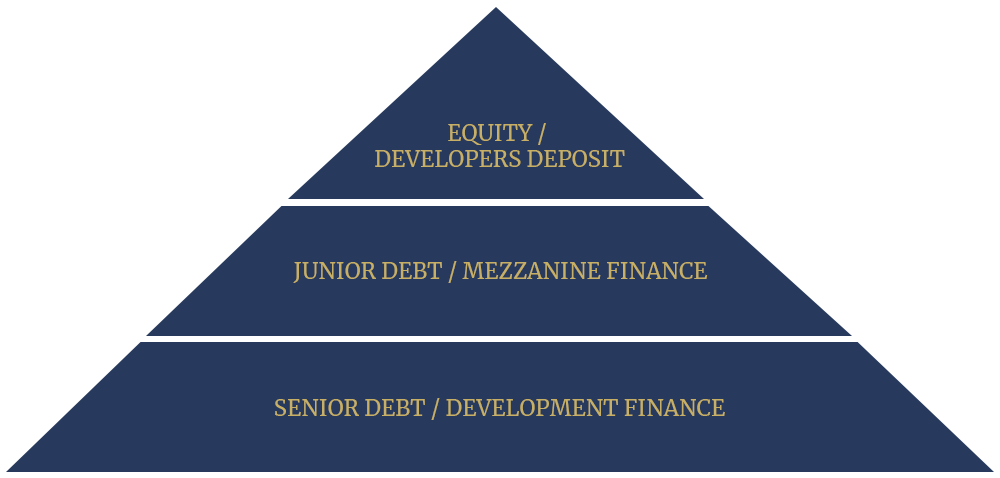
The 3 parts of funding for development projects

Senior debt / development finance
Senior debt can be used to finance all the build costs and part of the purchase costs. The lender will take a first legal charge against the land / building title(s).
Senior debt is usually capped at 65% LTGDV, 80% LTC and 70% LTV (The maximum loan is calculated using these three metrics as an assessment). There are some lenders whose metrics are a little higher.
There are several factors that are taken into consideration when a lender assesses your loan. The main factors are outlined below:
Junior debt / mezzanine finance
Mezzanine finance is accessed if there is a shortfall in Senior Debt loan funds. The lender will take a second legal charge against the land / building. This is more expensive to obtain (typically 15%-25%). The funds are used towards the purchase costs first, so you are being charged on the interest as soon as you are provided with the loan funds.
Equity finance / developers deposit
The developers deposit can come from a range of sources:
If the developer cannot put down a deposit, there are equity providers that will give developers funds to cover the deposit. Typically, this is completed as a joint venture (JV). Different equity providers structure the JVs in different ways. Some charge interest / coupon on the amount they provide AND take a profit share of the completed development.
Make sure you read the fine print in any JV agreement!
Additional security
The lenders may ask for additional security:
Repayment of loans
Once the development is complete, you will need to repay this finance. Please note that in most cases you cannot choose who you pay first. It usually is repaid in this order:
In most cases the developer gets paid last although this can be negotiated with the equity provider as part of the JV agreement.